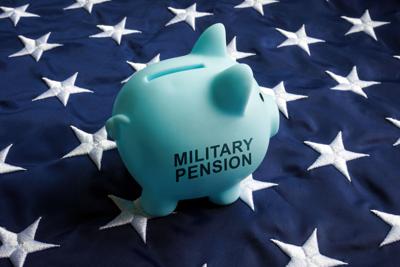

Military pension concept. Piggy bank with sign on flag.
Separating from the service typically means trading a predictable paycheck and subsidized housing for something entirely different: a monthly pension that must stretch to cover what your active-duty compensation once handled automatically. Getting that math right before you move is what helps separate a comfortable retirement from a stressful one.
The good news is that a military pension is a genuinely solid foundation. The work is understanding what surrounds it and building the rest of the budget accordingly.
Know Your Pension Number Cold
Before any other calculation, nail down the exact monthly take-home amount from your pension. That means your gross retired pay, minus any voluntary allotments and any premiums you pay for SBP coverage if you have a beneficiary you're protecting. If you waive a portion of retired pay to receive VA disability compensation, account for that offset as well. Some veterans receive both without a reduction through concurrent retirement and disability pay (CRDP), but eligibility depends on your disability rating. Start with the real net number, not the gross.
People are also reading…
Map the Benefits That Replace Old Expenses
Part of what makes military retirement work is that several major costs remain subsidized. Health coverage through Tricare typically runs far below what civilians pay for comparable insurance. If you're retiring before 65, budget for the Tricare Prime or Select premium and whatever copays apply to the care you use most. Once you hit Medicare eligibility, Tricare for Life layers on top, which substantially lowers out-of-pocket health costs.
Access to commissary and exchange privileges, access to base recreation facilities, and the ability to use MWR programs are real line items worth acknowledging. They help keep everyday expenses lower than many retirees expect.
Account for Where You're Choosing To Live
Your pension goes different distances depending on where you settle. State income tax treatment of military retirement pay varies significantly. Some states exempt it entirely; others tax it like ordinary income. That difference can add up to hundreds of dollars a month in take-home pay on the same pension.
Housing costs are the other major variable. In a Rocket Mortgage study on military retirement destinations, which surveyed more than 1,100 service members, veterans, and spouses, cost of living ranked as the second most important retirement priority, named by 23% of respondents — just behind health care access. That finding reflects a real tension veterans navigate: the cities with the most robust VA medical networks aren't always the most affordable ones. Getting both right takes deliberate research.
Build a Realistic Monthly Spending Plan
With your pension number and location in mind, lay out the full picture of what you'll actually spend. Group expenses into categories that make sense for your life:
Fixed monthly costs — mortgage or rent, any loan payments, Tricare premiums, SBP premiums, phone and utilities, and insurance.
Variable monthly costs — groceries, transportation and fuel, medical copays and prescriptions, dining, and personal care.
Annual costs spread monthly — property taxes, car registration, travel, home maintenance, and larger insurance premiums. Divide annual estimates by 12 and fold them into your monthly figure so they don't hit as surprises.
Add a buffer. Most financial planners recommend keeping three to six months of living expenses accessible. For veterans who own a home, a home equity line of credit can serve as a backstop without requiring a large liquid reserve.
Factor In Health Care Costs Over Time
Health care is the budget line most likely to grow as you age. While Tricare and VA care keep costs manageable for most veterans, out-of-pocket costs for prescriptions, specialist visits, and supplemental coverage do accumulate. If you have a service-connected disability rating, factor in any VA compensation payments as an additional income source that can offset these costs. If you anticipate needing long-term care support later, consider where that fits into your plan well before it becomes relevant.
Use the VA Loan Benefit Strategically
Buying a home in retirement is a meaningful decision, and veterans have an advantage worth understanding fully. The VA home loan benefit allows qualified buyers to purchase with no down payment and no private mortgage insurance. In a retirement budget where cash flow is the priority, keeping a down payment in liquid savings rather than converting it to equity can make sense. That flexibility, combined with competitive VA loan rates, means your mortgage payment can be lower than many civilians expect to pay for a comparable home.
Work with a lender who specializes in VA loans to model what different purchase prices mean for your monthly budget. Running those numbers before you commit to a city helps you know the maximum home price that still lets everything else work.
Review the Budget Every Year
A retirement budget isn't a document you write once and file away. Tricare premiums change. Pension cost-of-living adjustments arrive annually. Spending patterns shift as you settle into retired life. A quick annual review, ideally before the new year or when COLA figures are released, helps to keep your plan current and catch any drift before it compounds. Small adjustments made early are far easier to manage than large corrections made late.
This content is for informational purposes only and should not be construed as financial advice. Please consult a finance professional for financial advice. The views, thoughts and opinions expressed in this contributor content belong solely to the contributor and do not represent the views of Lee Enterprises. Lee Enterprises does not endorse the products, services or companies referenced. Readers are encouraged to carefully review the terms of service of any service provider.